Is FIRE right for you? What early retirement really takes
Is FIRE right for you? What early retirement really takes
Mon, 11/02/2026
The idea has never been more appealing: quit your 9-to-5 decades ahead of schedule and spend your days on your own terms. You may have heard of the FIRE movement, but what is it really and does the hype live up to reality?
FIRE stands for Financial Independence, Retire Early.
While some FIRE advocates focus on retiring early, others are more interested in achieving enough financial independence to gain greater flexibility over their career, lifestyle and future.
Wherever your goal fall on that spectrum, FIRE is typically built around three commitments: high savings, frugal living and disciplined investing. Proponents generally save from 50-75% of their yearly income, according to CNBC Select, live more frugally and invest those savings for growth potential over time.
Why FIRE resonates with some people
• It can help you prioritize. While you may want a long and successful career, you may instead prioritize earlier retirement or a path that allows you more time with family, a more meaningful job or a downshift from your current daily grind.
• It advocates for some sound financial principles. Living within your means, saving for your goals and investing for long-term growth potential can help build a solid financial foundation.
• It helps you set a strategy for the future. Achieving your retirement goal is easier when you've defined what you want retirement to look like and built a strategy to help achieve it.
What to consider before pursuing FIRE
• Your budget may change. Future expenses may look different than they do today. Family obligations, emergencies and other life changes can increase the amount you'll need in early retirement.
• You may need to bridge the retirement benefit gap. Medicare covers many healthcare costs for retirees 65+, but if you retire early, you'll need to find and pay for health insurance until you become eligible. You'll also need to rely more heavily on personal savings for longer before claiming Social Security benefits. Because Social Security benefits are generally based on your highest 35 earning years, retiring early may result in a lower benefit than if you'd continued working.
• Your flexibility may be limited. Market declines can be particularly challenging in retirement. One way to help weather a decline is by reducing spending, but a lean budget with more necessary expenses may leave you with fewer options to adjust your spending.
• Your strategy should be personalized. Many FIRE proponents advocate for rules of thumb like the 4% withdrawal rate and saving 25 times your annual expenses. However, retiring earlier than normal means your savings must support a longer retirement, and inflation has a larger impact. Therefore, your withdrawal rate may need to be lower and your planned savings higher than traditional rules of thumb, and those targets should be personalized to you.
Start planning now
Whether your goal is early retirement or a more traditional path, a financial advisor can help you with a plan for your goals and the path ahead.
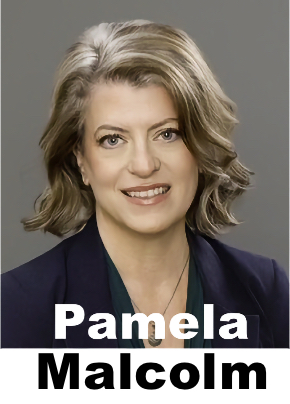
This content was provided by Edward Jones for use by Pamela Malcolm, your Edward Jones financial advisor at 3727 California AVE SW #1D, (206) 489-0035. Edward Jones and its financial advisors cannot provide tax advice. You should consult your qualified tax professional regarding your situation.
Edward Jones-Member SIPC
Pamela G. Malcolm
Financial Advisor – Edward Jones
(text capable for clients)
📍 3727 California Ave. SW #1D, Seattle, WA 98116